Library
Ground lease (erfpacht) in the Netherlands: how does it affect your mortgage?
Buying a home with erfpacht? Learn how a ground lease affects your Dutch mortgage, borrowing capacity, monthly costs and what to check before making an offer.
Foundation problems in the Netherlands: what they mean for your mortgage
Buying a Dutch home? Learn how foundation problems can affect your mortgage, repair budget and property value, and what to check before making an offer.
What to check about a VvE before you buy a Dutch apartment
What a VvE is, what the reserve fund must hold by law, what self-management costs you in time, and how lenders judge it. With a 10-point checklist.
Questions to ask a mortgage advisor in the Netherlands
Choosing a mortgage advisor in the Netherlands? Discover 10 essential questions to ask about fees, independence, mortgage lenders and expat eligibility. Learn how to compare advisors, understand hidden costs and find the right mortgage advice for your situation.
Financial advisor for expats in the Netherlands: who can help you buy a home?
Looking for a financial advisor in the Netherlands to buy a home? What a mortgage advisor and a financial planner cover, what it costs and how to check them.
Rent or buy in the Netherlands: what the housing market data means for expats
Rents in Amsterdam, Rotterdam and Utrecht keep rising while landlords sell. See the 2026 data on rents, house prices and mortgage rates, and what to choose.
Gift tax in the Netherlands for expats: using a gift from your parents to buy a home
Parents abroad giving you money for a Dutch home? See when Dutch gift tax applies in 2026, what you must declare and which papers your lender asks for.
WOZ value and property tax in the Netherlands: what expats pay in 2026
What the WOZ value is, how your municipality sets it, which Dutch property taxes it drives and what a higher WOZ value costs you. 2026 figures and the 2027 outlook.
30% ruling becomes 27% in 2027: what it means for your Dutch mortgage
The 30% ruling becomes 27% in 2027. Who keeps 30%, what 27% does to your take-home pay, how Dutch lenders treat the expat ruling and what to plan before it ends.
Transfer tax in the Netherlands 2027: rates and exemptions
Dutch transfer tax in 2027: 2% for your own home, 0% under the startersvrijstelling up to €615,000, 7% for rentals and second homes. Rates, conditions and examples for expats.
Prinsjesdag 2026: what changes for your mortgage and home in 2027
Prinsjesdag 2026 sets the tax, housing and mortgage rules for 2027. See what changes for expats: interest deduction, transfer tax, 30% ruling and energy rules.
Do you need a Dutch bank account to get a mortgage in the Netherlands?
A Dutch bank account is usually required to complete your home purchase, but it does not affect which lender approves your mortgage. Find out why.
Which Dutch mortgage lenders work with expats, and how do you reach them?
Most Dutch mortgage lenders are not banks, and many cannot be approached directly. Learn how the market is structured and how to reach every option.
Buying a home in Eindhoven as an expat: what you need to know
Buying a home in Eindhoven as an expat? OHAO explains mortgages for tech workers, the 30% ruling, foreign income, and the local housing market in 2026.
Buying a house in Amsterdam: what makes it different from the rest of the Netherlands
Amsterdam has unique rules: erfpacht, overbidding, VvE, and big price gaps between districts. Learn what expats need to know before buying in 2026.
Buying a home in The Hague as an expat: what you need to know
Planning to buy a home in The Hague as an expat? OHAO explains mortgages for foreign income, 30% ruling, and self-employed internationals in Den Haag.
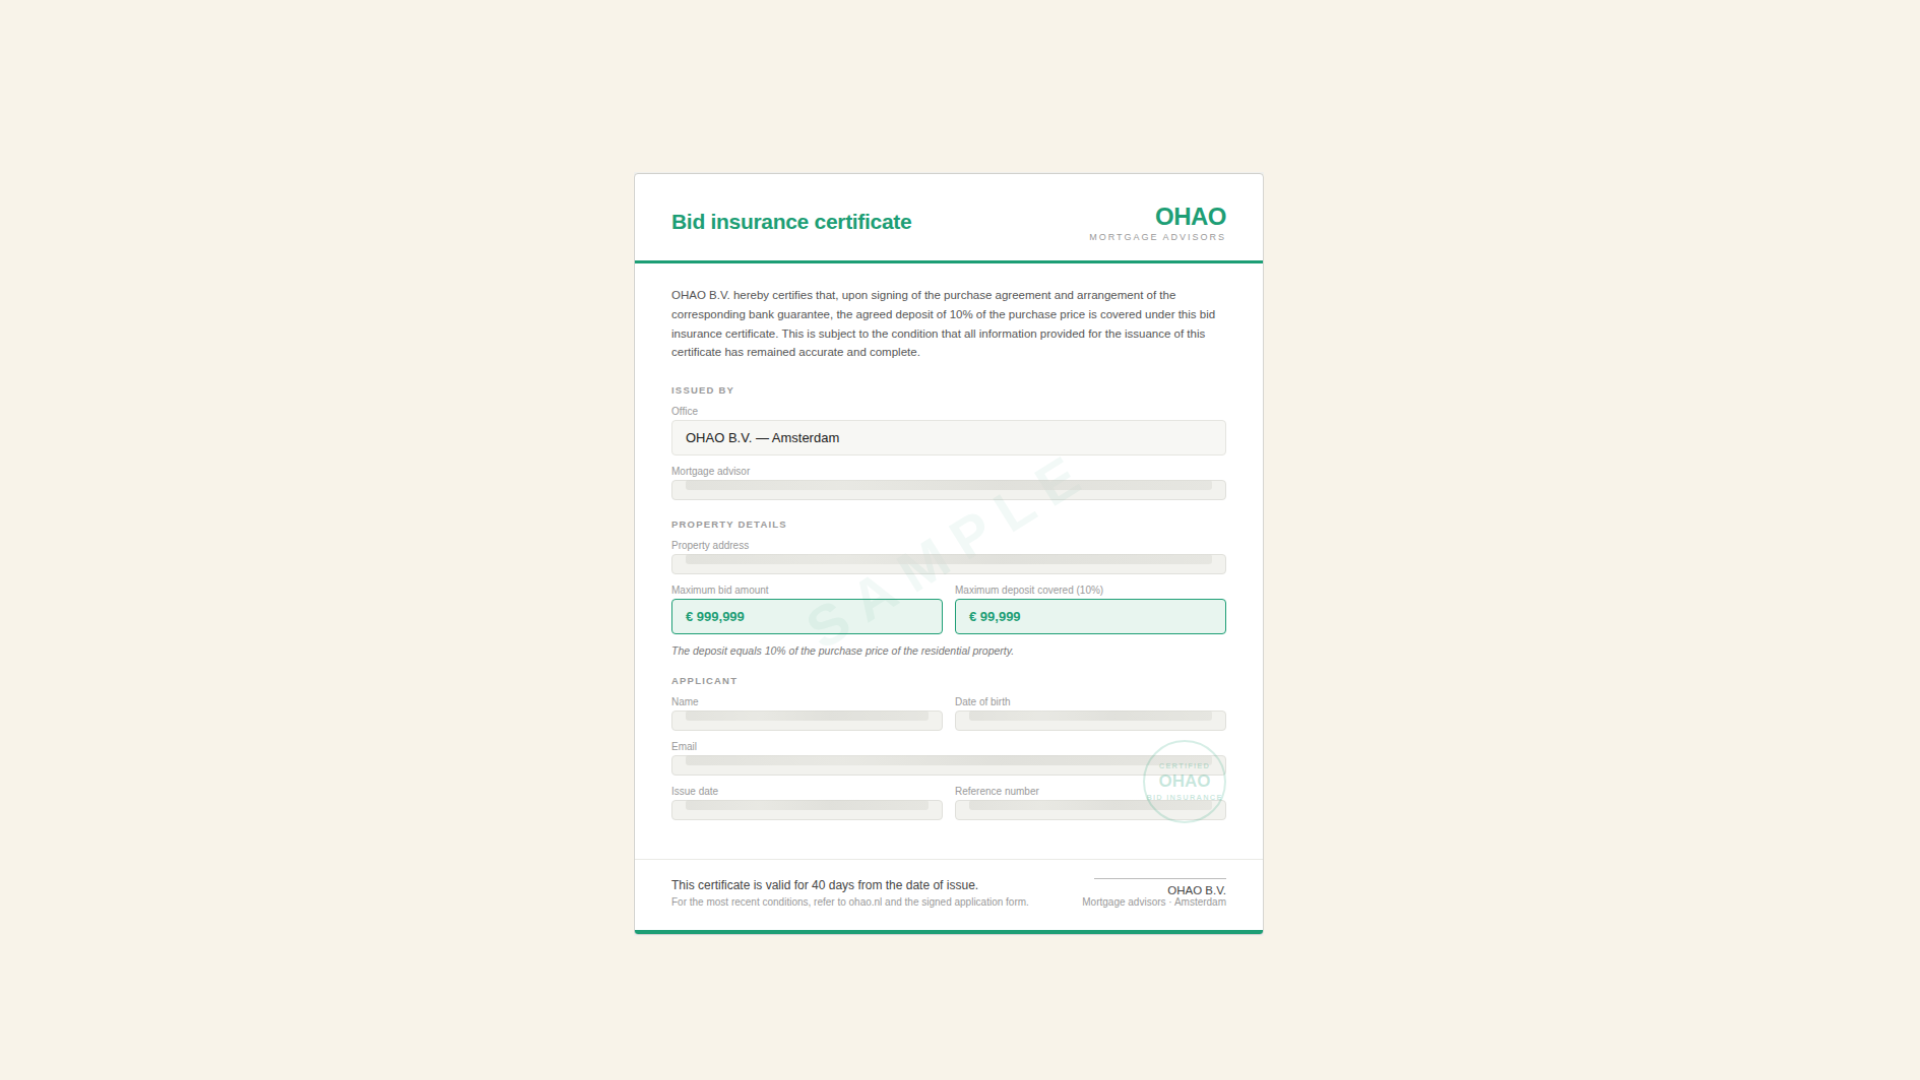
How bid insurance works for homebuyers in the Netherlands
Learn how bid insurance protects you when bidding without a financing clause in the Netherlands. Understand costs, coverage, and eligibility for expats.
Dutch purchase agreement explained
What are the resolutive conditions when buying a house in the Netherlands? Learn which ones to include and how they protect your 10% deposit.
The 10% penalty when buying a house in the Netherlands
Learn when the 10% deposit penalty applies when buying a home in the Netherlands, how much it could cost you, and 4 ways to avoid it as an expat.
Bidding without a financing clause in the Netherlands
Should you bid without a financing clause? Learn the risks, benefits, and how to protect yourself as a homebuyer in the Netherlands.
Iran war and Dutch mortgage rates in 2026
How does the Iran war affect Dutch mortgage rates? See what the ECB, Fed, and Dutch banks forecast for interest rates in the Netherlands.
Can U.S. citizens get a mortgage and buy a house in the Netherlands?
U.S. citizens can legally buy property and qualify for mortgages in the Netherlands. As long as you have the right documents, such as a BSN number and proof of income, the process is similar to that for Dutch residents.
How much can you borrow with a Dutch mortgage in 2026?
Learn how much mortgage you can borrow in the Netherlands in 2026, including NHG limits, income rules, energy labels, student loans (DUO), BKR impact, and expat considerations.
30% ruling and your Dutch mortgage: what expats need to know
How the 30% ruling affects your mortgage calculation, what happens when it expires, the 2027 reduction to 27%, and how to maximise your borrowing power as a skilled migrant in the Netherlands.
Holiday allowance, bonuses, and salary components in your Dutch mortgage (2026)
How Dutch lenders treat holiday pay, 13th month, overtime, commissions, choice budgets, and future salary increases — and how to maximise your mortgage income in the Netherlands.
How debts affect your Dutch mortgage: DUO, BKR, loans, and more (2026)
Student loans, BKR registrations, personal loans, car leases, alimony, and buy-now-pay-later — how each debt type reduces your maximum mortgage in the Netherlands and what to do about it.
Buying a home together: the legal and financial checklist for 2026
Financial obligations when buying a property together: cohabitation agreements, ownership splits, and everything to arrange before buying together in the Netherlands.

How much mortgage can I get alone vs. together in the Netherlands?
Compare mortgage borrowing power as a single buyer vs. a couple in 2026. Covers the €18,000 single-buyer bonus, income variables, self-employed rules, family donations, family mortgages, and when buying alone is the smarter move.
Mortgage and ZZP’er in the Netherlands (2026 Guide)
A complete 2026 guide for ZZP’ers in the Netherlands explaining how mortgage lenders assess self-employed income, which documents are required, NHG rules, and how to improve your approval chances.

New to Utrecht and buying your first home in 2026?
Thinking about buying your first home in the Utrecht area in 2026? Discover mortgage requirements, borrowing capacity, savings needed, and practical tips for expats entering the Dutch housing market.
Step-by-step home buying guide for expats in the Netherlands (2026)
A complete guide for expats buying a home in the Netherlands in 2026 — from checking your mortgage eligibility to collecting your keys at the notary.
Moving homes in the Netherlands: a clear guide to bridging loans
A clear, practical guide explaining how bridging loans work in the Netherlands, when they are used, the requirements, risks, and tax considerations for homeowners buying a new property.
Can I increase mortgage in the Netherlands?
A clear guide and explanation of how increasing your mortgage in the Netherlands works, including the requirements and available options.
Buying a home together in the Netherlands: what you need to know
Buying a home together in the Netherlands with a partner, friends, or family can increase borrowing power—but it requires clear legal and financial agreements.
Mortgage application approval in the Netherlands: what to expect
Buying a home in the Netherlands? Learn how how long mortgage application can take and what to expect when buying a home in the Netherlands.
How the maximum mortgage is calculated in the Netherlands?
In the Netherlands, your maximum mortgage is calculated using regulated affordability rules based on your gross income (including salary, holiday pay, and structural bonuses), mortgage interest rates, and fixed-rate period. Lenders also assess your financial obligations, the 100% loan-to-value limit, and the property’s market value and energy label.
Can you get a mortgage with a temporary contract in the Netherlands?
Can you get a mortgage in the Netherlands with a temporary contract? Yes. Bart explains what lenders look at, when they use your full salary, and what it means for how much you can borrow.
Getting a mortgage with non-traditional income in the Netherlands
Applying for a mortgage with non-traditional income in the Netherlands can be complex. This guide explains how Dutch lenders assess income from BV owners, ZZP freelancers, foreign salaries, and the 30% ruling, and what you need to prepare for approval.
Can you get a mortgage with a foreign income in the Netherlands?
Getting a mortgage in the Netherlands with a foreign income is possible, but banks assess additional factors such as currency risk, income stability, and employment structure. Foreign income is typically converted into euros and may be reduced by a safety margin.
Mortgage advisor fees in the Netherlands: what to expect
With OHAO, you benefit from one of the best-value mortgage advisory fees in the Netherlands. Our expert guidance ensures high-quality support for both Dutch buyers and Expats at a fair, transparent fee.
Best Mortgage Advisors in the Netherlands – OHAO
Discover why the mortgage advisors at OHAO are considered among the best in the Netherlands — offering transparent fees, exceptional service, and access to 40+ lenders.
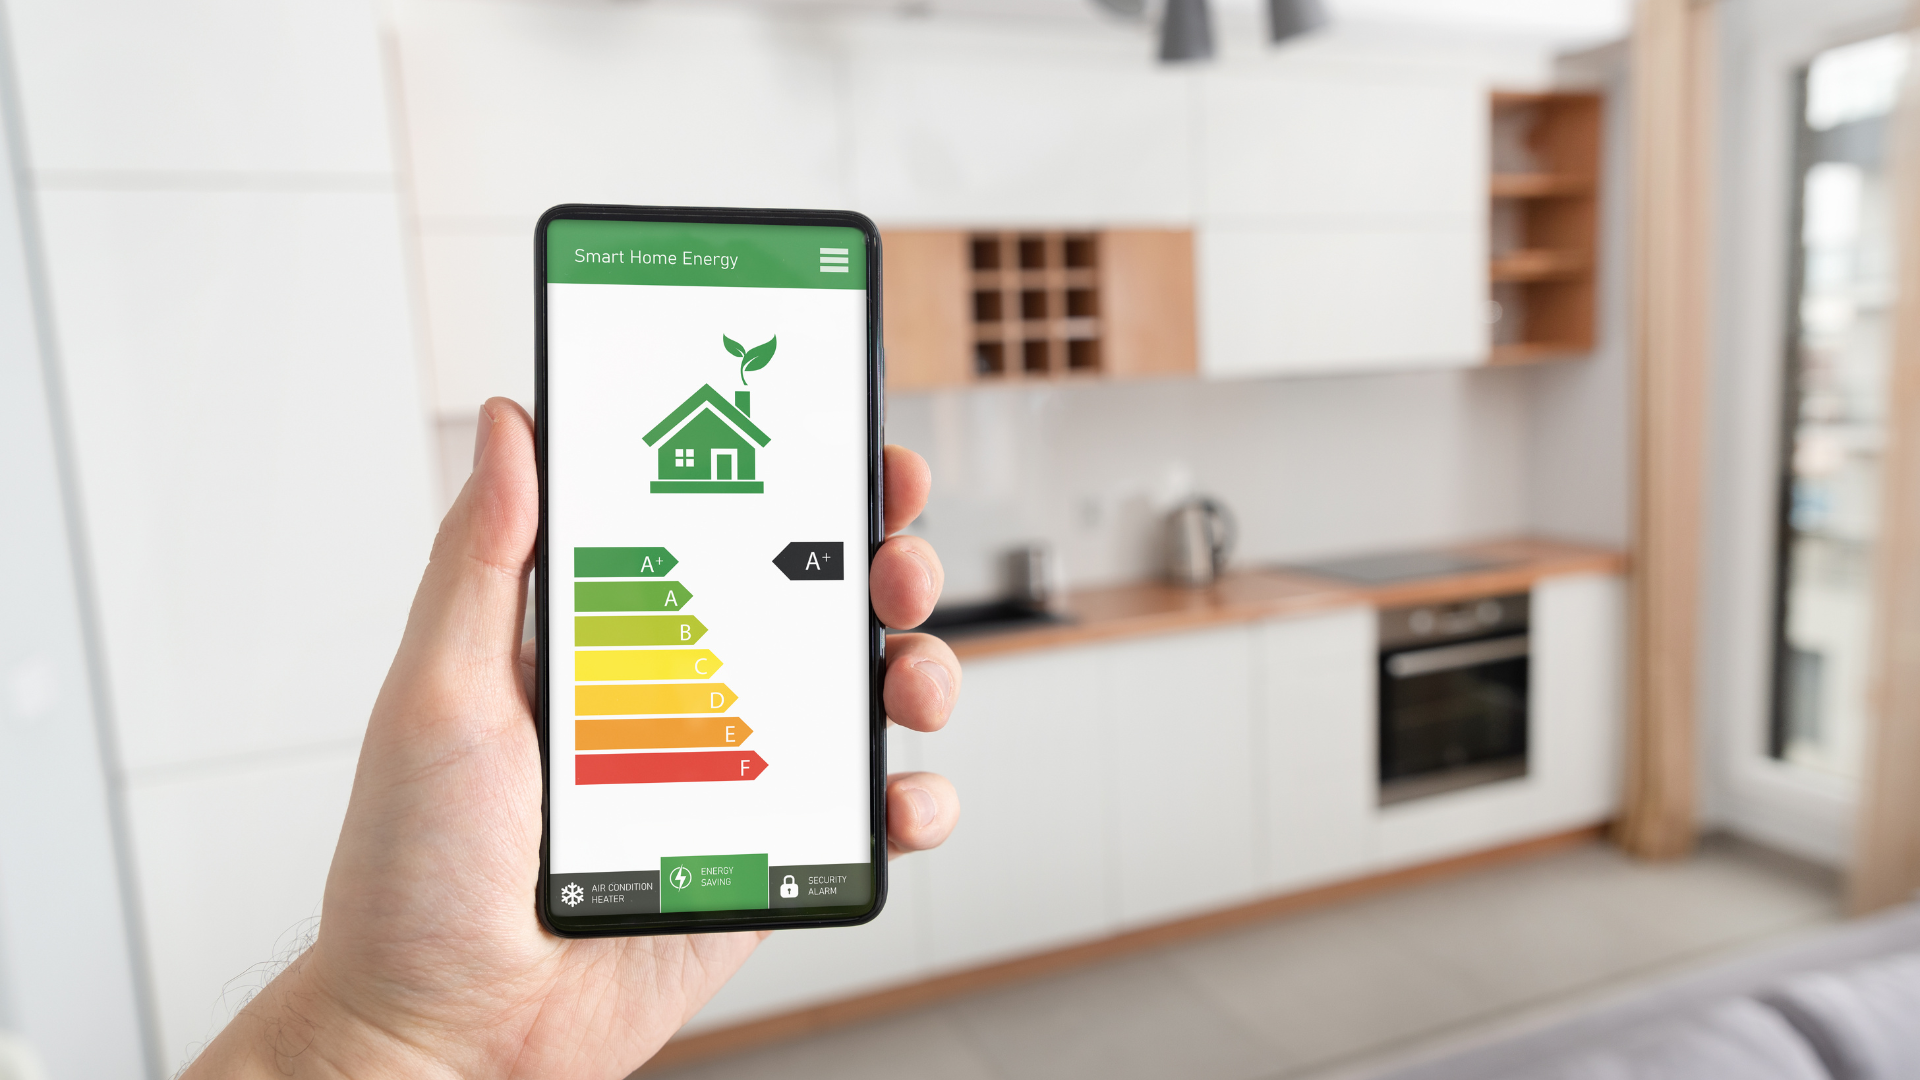
Better energy label, higher mortgage ( Updated 2026)
Your energy label now directly influences your maximum mortgage in the Netherlands. Properties with better energy labels allow for higher borrowing because their lower energy bills leave more room in your monthly budget.
How do you buy and finance a new-build home?
Buying a new-build home in the Netherlands works differently than purchasing an existing property, especially for expats navigating the market for the first time. This short guide explains why a new-build can be an excellent choice and how the process works.
How a bank guarantee works when buying a home in the Netherlands
A bank guarantee is an important part of the Dutch home-buying process, especially if you don’t want to pay the 10% deposit from your own savings. Read our blog to learn more about how it works and when you might need one.
Buying a home in the Netherlands: with or without a financial clause?
Deciding whether to buy a home in the Netherlands with or without a financial clause is an important step that can greatly influence your financial security and the overall buying process. Read our article to learn more

How BV (business owners) can get a mortgage in the Netherlands (2026 update)
As a BV business owner, securing a mortgage in the Netherlands comes with unique rules around income, stability, and financial structure. With the right preparation, you can significantly increase your approval chances and access better rates — here’s how to get started.
Understanding the 3-day reflection period in the Netherlands
Make confident decisions when buying a home in the Netherlands. Our specialists help you understand the 3-day reflection period and guide you through every step of the purchase process. Get expert support before you sign.
New build project: how to get a mortgage in the Netherlands
To get a mortgage for a new-build home in the Netherlands, secure a construction-ready purchase contract and provide your lender with the building specifications, cost breakdown, and expected completion timeline. Read our article for more information.
Winning your bid: house bidding tips for the Dutch housing market
Buying a home in the Netherlands can be competitive and fast-paced. With the right bidding strategy, you can improve your chances of getting your offer accepted.
Can I get a mortgage in the Netherlands? (Updated 2026)
Many internationals planning to buy a home in the Netherlands wonder whether they qualify for a Dutch mortgage. With the 2026 lending rules now in effect, understanding the eligibility requirements has become even more important for expats and first-time buyers.
How to make your offer stand out in the Dutch housing market ( 2026)
Preparation is the key factor that separates successful buyers from the rest in the Dutch housing market. Here are two main factors that can help you gain that advantage.
How much savings do you need to buy a home (updated 2026)
Buying a home in the Netherlands requires more than just a mortgage — you also need savings to cover taxes, fees, and additional purchase costs. This updated 2026 guide explains exactly how much you should prepare and what expenses to expect as a homebuyer.
Why do I need a mortgage broker in the Netherlands?
A mortgage broker guides you through the complex Dutch mortgage system and helps you avoid costly mistakes. They negotiate better deals, lower fees, and secure the right mortgage for your situation.
Mortgage application document checklist (2026 Update)
Mortgage regulations in the Netherlands may change each year, but the required documents for expats remain mostly the same. For 2026, expats can expect lenders to ask for the standard proof of income, employment, residency, and financial stability.
How much will you be able to borrow in 2026
In 2026, borrowing capacity will change due to updated Nibud calculations, wage growth, and new energy-label rules. Most buyers will see modest increases, with larger effects for higher incomes and energy-efficient homes.
7 Key Benefits First-Time Buyers Can Take Advantage of in 2026
Many discuss the steps to buying a home, but few highlight the real benefits of the Dutch mortgage system. These hidden financial and tax advantages can greatly support you as a first-time buyer.
Bridging loans explained: how to finance your next home before you sell
Buying your next home before selling your current one is possible in the Netherlands if you use a bridging loan. This financial tool allows you to unlock your equity early and finance your next purchase before your sale completes. Here is how it works step-by-step.

National Mortgage Guarantee (NHG) in 2027: mortgage limit rises to €500,000
The NHG limit rises to €500,000 in 2027 (€530,000 with energy-saving measures). See which date counts, what NHG costs and how much it saves you.

6 Smart ways to use your home equity in NL
If you have built up some equity on your current home, it might be interesting to use it for something else. Here we will discuss some of the options you have to use it to your advantage. Please take into account that a mortgage provider will not only look at the current value of your home but also at your current income situation to determine the amount.
How to choose the right mortgage in the Netherlands?
Once you manage to acquire a home you might need to apply for a mortgage. In this process you are faced with a number of important choices that have a major impact on your monthly payments. Here we will tell you all about the choices you can make and learn more about the pros, cons and consequences of all these choices.

How to make a home more sustainable inthe Netherlands
A sustainable home will create a healthier environment for you, your family and the world. It will also add to a more comfortable indoor climate, help you safe costs on your electricity bill and create more value for your house. But where to start? We can help you explore all financial options for a better and greener home.

Buy-to-let mortgage guide Netherlands
Did you ever consider buying a property just to rent it out? The extra income might be handsome enough to spark the interest. We guide you through the pros and cons of renting out homes and what steps you need to take.
Mortgage interest rate deductions: 2026 outlook
Mortgage interest deductions let homeowners lower their taxable income by the interest paid on their loans. In 2026, key tax changes could affect how much you can deduct. Stay informed to make the most of your tax benefits.
The housing market and prices in the Netherlands 2026: What to Expect in 2027
House prices in the Netherlands are still rising in 2026, but more slowly. See what the big banks expect for 2027 and what it means if you plan to buy a home.
Mortgage interest rates Netherlands 2026-2027 outlook
Why Dutch mortgage rates rose in 2026, and what the ECB and Dutch banks expect for 2027.
Maximum mortgage in the Netherlands 2026
Buying a home in the Netherlands in 2026? Find out exactly how much mortgage you can afford based on updated income ratios, interest rates, and national lending limits. Get clear answers before you start house hunting.

NHG 2026: what’s changing and why it matters
The National Mortgage Guarantee (NHG) protects Dutch homeowners and lenders against financial loss if a property is sold for less than the mortgage. In 2026, the NHG limit will rise from €450,000 to €470,000, or up to €498,200 for energy-efficient homes.

Mortgage options for renovations
Why should you think about moving, when you could also make your current house bigger, more cosy or more energy efficient? Renovation will of course cost you money, and you could choose to use your savings for this. If you don't have sufficient savings, or when you do not want to you use your savings for this purpose, it's good to find out whether it's possible to increase your current mortage. Below you'll read more.
Property transfer tax 2026
In the Netherlands, transfer tax is a one-time fee paid when purchasing a property, with different rates applicable to homeowners and investors. From 2026, the tax rate on investment properties will decrease, while the exemption threshold for first-time buyers will increase.
Budget Day: what new regulations to expect in 2026?
Each year in the Netherlands, the government presents its budget plan on Prince’s Day (Prinsjesdag). Read our blog to learn about the key financial policies and tax changes that will take effect in 2026.
Loan-to-value in the Netherlands: a guide for first-time homebuyers
Are you a first-time homebuyer?Do you wonder how much you can borrow in the Netherlands? One of the benefits of buying a home here is that you can borrow up to 100% of the property’s value (loan-to-value). Read on to learn more.
Which mortgage closing fees are tax-deductible in the Netherlands?
If you are an expat in the Netherlands and plan to buy a home, you may be surprised that some mortgage fees are tax-deductible. Find out which mortgage fees are tax-deductible and how much you can expect to get back after filing your tax return.
First-time buyer mortgage with NHG in 2026 and 2027: what you need to know
If you are a first-time homebuyer in the Netherlands, an NHG-backed mortgage can offer extra financial security. NHG (Nationale Hypotheek Garantie) helps protect you if you can’t keep up with your mortgage due to unexpected life events. Read our article to learn more.
Variable mortgage interest rate in the Netherlands: is it the right choice for you?
Is a variable mortgage interest rate right for you? Discover the pros and cons of choosing a variable rate and how it could impact your monthly payments. While it often starts with lower rates, it can fluctuate with the market, offering potential savings or unexpected costs.
Fixed mortgage interest rates in the Netherlands: everything you need to know
A fixed mortgage interest rate means your interest rate stays the same for a set period— most popular fix periods 5, 10, 20, or even 30 years. This gives you predictable monthly payments, making it easier to budget long-term. In the Netherlands, many homebuyers choose fixed rates for stability and protection against future rate increases.
Why do mortgage interest rates increase or decrease?
What influences mortgage interest rates to increase or decrease? Which factors play an important role, and how can you recognize trends that help you make the right decision? For more information, read our article.
Mortgage interest types explained in the Netherlands
What do you need to know about mortgage interest rates in the Netherlands? How can you decide on which interest rate is the best for you: should you choose a variable or fixed interest rate? Who can help you make the right decision? Which factors influence mortgage interest rates? What should you do when a fixed interest rate ends, or can you switch in the middle of the term? Find all the answers in our blog.

Increase your mortgage to access your home equity
If you have owned your home for some time, its value may have increased beyond your remaining mortgage balance, giving you excess equity. This equity can be used in many ways, whether for home renovations, a major purchase like a car, or other financial needs. On this page, you find all the essential information on accessing and withdrawing your home equity.

Increasing your mortgage for renovation
Why should you think about moving, when you could also make your current house bigger, more cosy or more energy efficient? Renovation will of course cost you money, and you could choose to use your savings for this. If you don't have sufficient savings, or when you do not want to you use your savings for this purpose, it's good to find out whether it's possible to increase your current mortage. Below you'll read more.
Reviews from our customers
Every day, we strive for 5-star service, as this is the minimum for us. That’s why we are so proud of the feedback we receive from our customers:
Meet our mortgage advisors
Our mission is to find the perfect mortgage for you and to guide you through every step of the home-buying process, no matter your situation. Book a free consultation today.
Bart Kooijman
Mortgage Advisor

Luc Zwaan
Mortgage Advisor
Toni van der Flier
Mortgage Advisor
Robin Uijtdehaage
Mortgage Advisor