Toni van der Flier
Mortgage Advisor at OHAO
28 July 2025 · Updated 28 Aug 2026 · 6 min read
Key takeaways
The standard limit is 100% LTV — a €400,000 appraised home can be fully financed, but closing costs of roughly 5–6% still come from your savings.
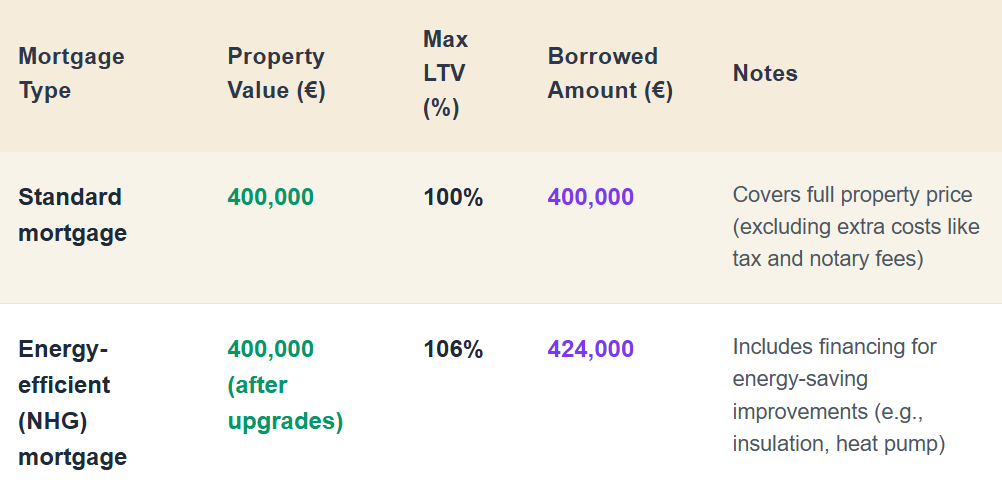
Energy-saving improvements can push you to 106% LTV, so a €400,000 home could support a €424,000 mortgage covering the upgrades.
LTV drives your rate: borrowing 100% is priced as higher risk, while dropping below 65% earns a lower rate — and rising home value can remove the surcharge mid-term.
In the Netherlands, homebuyers can borrow up to 100% of a property’s value through a mortgage, covering the full purchase price but excluding additional costs like taxes and notary fees. Those making energy-efficient improvements may qualify for a higher loan-to-value (LTV) ratio of up to 106% under the National Mortgage Guarantee (NHG). This article was written by Toni our mortgage advisor at OHAO, who explains how your LTV and property value can influence your mortgage interest rate.
How much mortgage you can get in the Netherlands?
In the Netherlands, you can borrow 100% loan-to-value (LTV) when you buy a home. In this case, your mortgage covers the full purchase price of a property, as long as the value has been confirmed by a certified appraiser.
For example, if the property is valued at €400,000 and the maximum LTV is 100%, you can borrow the full amount of €400,000. However, if the LTV is 90%, you can only borrow €360,000, and you need to contribute the remaining €40,000 as a down payment.
Keep in mind that additional costs — such as transfer tax, notary fees, and the property valuation report — cannot be included in your mortgage. You need to cover these expenses from your own pocket, which typically add up to around 5–6% of the purchase price.
What is a loan-to-value (LTV) for energy-efficient homes?
In the Netherlands, the standard loan-to-value (LTV) limit for mortgages is 100% of your home’s appraised value.
If you plan to make your home more energy-efficient — for example, by adding insulation, installing a high-efficiency boiler, or using a heat pump — you may be able to borrow more.
With some mortgage lenders or when using a National Mortgage Guarantee (NHG), you can borrow up to 106% of the appraised property value. This means you can finance energy-saving improvements on top of the full purchase price.
For example, if your home is valued at €400,000 after renovations, you could borrow up to €424,000 (106% LTV) to cover both the home purchase and the energy-efficient upgrades.
Does LTV impact your mortgage interest rate?
Yes, LTV (Loan-to-Value) directly impacts your mortgage interest rate.
If your LTV is high — for example, you want to borrow 100% of the property’s value — the bank sees that as a higher risk. In this case, you can expect a higher interest rate.
If your LTV is lower — for example, below 65% — it means you are using more of your own money. Your mortgage lender sees this as less risky, which means you can expect a lower interest rate.
Do you want to compare how LTV impacts mortgage interest rates? Use our interest rate comparison tool to see the latest rates from over 40 mortgage lenders in the Netherlands.
How does an increase in home value affect your mortgage interest rate and loan-to-value?
Let’s say you bought a home some time ago, and its value has since increased. You could benefit from this by lowering your mortgage interest rate. Why? Because many mortgage lenders add a surcharge — an extra cost — when your loan represents a large portion of your home’s value.
If your home’s value rises, this surcharge may decrease or even disappear, which can reduce your monthly payments. Some lenders allow you to request this adjustment during your mortgage term.
If this applies to you, contact your mortgage lender or reach out to our mortgage advisors for help.
Talk to the OHAO team
Let’s look at your mortgage options
Whether you are just getting started or already taking the next step, we will look at your situation, answer your questions, and clearly explain your Dutch mortgage options.
Toni van der FlierMortgage Advisor
Book a free consultation with our team
Do you want to know how much mortgage you can borrow in the Netherlands? With over 10 years of experience working with expats, we are here to help you find the best mortgage option.
Luc Zwaan
Mortgage Advisor
Robin Uijtdehaage
Mortgage Advisor
Bart Kooijman
Mortgage Advisor

Toni van der Flier
Mortgage Advisor
Our happy clients
We are proud that so many clients appreciate the care, clarity, and high standards we bring to every mortgage journey.