Dutch mortgage calculator for expats – how much can you borrow in the Netherlands?
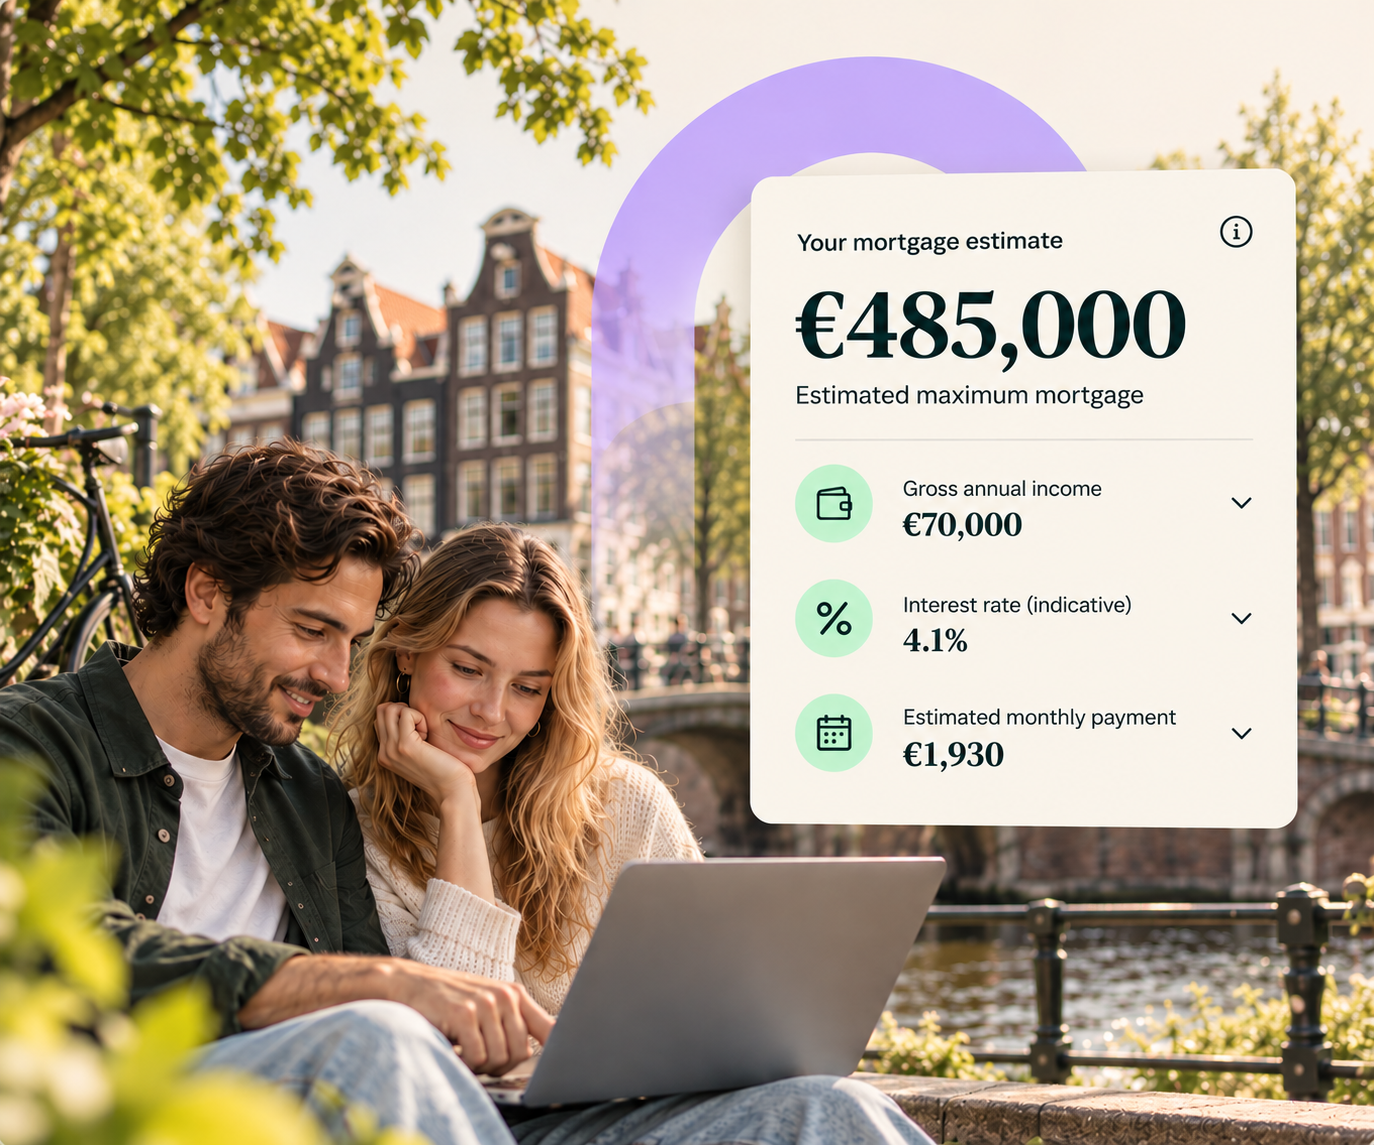
Buying a home in the Netherlands as an expat? Use our free mortgage calculator to estimate how much you can borrow and what your monthly payments could be, based on your income, the interest rate, and the home's energy label.
For a complete overview reviewed by a mortgage advisor, schedule a free call with our team. During your first consultation, we calculate your maximum mortgage and explain your options.
Your real maximum can be higher than this estimate
An online calculator provides an indication, not a mortgage offer. Lenders differ in how they assess holiday pay, bonuses, the 30% ruling, foreign income, student loans, and partner income, so two people with the same salary can have very different borrowing capacities. During our free introductory call, we calculate your maximum mortgage based on your personal situation and provide you with a personalised mortgage report.
What determines your maximum mortgage?
Lenders in the Netherlands use the same national lending norms, but how they apply them to your situation differs. These are the factors that decide how much you can borrow.
Income: your gross annual income is the starting point. Holiday pay, a thirteenth month and structural bonuses can count too, depending on the lender.
Interest rate: the interest rate you select directly influences your maximum mortgage and your monthly payment. A lower rate means you can borrow more for the same monthly cost.
Mortgage term: most Dutch mortgages run for 30 years. A shorter term means higher monthly payments and a lower maximum.
Existing debts: student loans, credit cards, car leases and other financial obligations reduce your borrowing capacity, even if you never use the credit limit.
Home value and type: the property's value sets the ceiling, since you can borrow up to 100% of it. The type of home and whether it qualifies for NHG also matter.
Energy label: homes with energy label A or B allow extra borrowing, and financing energy improvements can raise your maximum further.
30% ruling and foreign income: lenders calculate on gross income. Some include the 30% ruling for the years you remain eligible, and some accept foreign income or a partner's income from abroad. We can help you with it.
How do we calculate your maximum mortgage at OHAO?
We begin with a free consultation, during which our mortgage advisors gather key information—such as your income, holiday pay, and bonuses—to calculate an accurate estimate of your maximum mortgage.
Each client receives a personalized report that not only outlines their potential borrowing capacity but also provides a clear overview of monthly payments, closing costs, and tax-deductible expenses.
With this insight, you are fully prepared to search for your ideal home and place competitive bids. If required, our team can also issue a bidding certificate, giving you added strength and credibility as a buyer.
- Expat mortgage experts
- Clear, fast, and personal guidance
How mortgages work in the Netherlands
No formal pre-approval: unlike in the US or another EU countries, Dutch lenders don't pre-approve mortgages. Instead, your advisor calculates your exact maximum before you bid, and OHAO can issue a bidding certificate that shows sellers your financing is solid.
Bid first, apply after: the mortgage application starts once your offer is accepted. You usually have a financing condition of a few weeks, so having your documents ready in advance matters.
Application processing time: lenders typically take 5–10 business days to process an application, and longer in busy periods. A complete file from day one is the best way to avoid delays.
40+ mortgage lenders: the Netherlands has over 40 lenders, each with its own rules on bonuses, foreign income and the 30% ruling. We compare all of them to find the one that fits your situation, not just the lowest rate.
FAQ
How do mortgages work in the Netherlands?
No formal pre-approval: Unlike in the US or some other countries, formal mortgage pre-approval is not common in the Netherlands. Before you place a bid, your mortgage advisor can calculate your maximum borrowing capacity. OHAO can also provide a bidding certificate to support your offer.
Bid first, apply after: Your mortgage application usually starts once your offer has been accepted. If your offer includes a financing condition, you normally have a limited period to arrange your mortgage, so having your documents ready in advance can help you move quickly.
Application processing time: Lenders typically take around 5–10 business days to assess a mortgage application, depending on the lender, your situation, and whether additional information is required. Having a complete file from the start can help avoid unnecessary delays.
Compare 40+ mortgage lenders: Different lenders have different criteria for factors such as bonuses, foreign income, temporary contracts, and the 30% ruling. At OHAO, we compare mortgage options from 40+ lenders to find a solution that fits your situation — not simply the lowest interest rate.
How much mortgage can I get in the Netherlands as an expat?
Your maximum mortgage in the Netherlands depends on several factors, including your income, the interest rate, existing debts, your partner's income, and the home's energy label. Expats generally follow the same Dutch lending standards as other buyers, but your mortgage options can depend on how individual lenders assess your income and residency situation.
Use the calculator above for an estimate, or book a free call with our mortgage advisors for a personalised mortgage calculation.
Does the 30% ruling( 27% from 2027) increase my mortgage?
It can, depending on the lender. Dutch lenders calculate your maximum on gross income, and several include the 30% ruling for the years you remain eligible, which raises your borrowing capacity. Once the ruling ends, the calculation is based on your salary at that time. For more information, please contact our mortgage advisors directly.
How accurate is a Dutch mortgage calculator?
A mortgage calculator gives a realistic estimate, not a final mortgage offer. It follows the Dutch lending standards, but lenders may differ in how they assess holiday pay, bonuses, student loans, foreign income, and temporary contracts. This means that two people with the same salary may have different maximum mortgage amounts.
We recommend scheduling a free call with one of our mortgage advisors. By uploading a few documents beforehand, we can calculate a more accurate estimate based on your personal situation.
Reviews from our happy clients
We focus on delivering great results — and our clients’ feedback tells the rest of the story.