Dutch mortgage interest rates today – compare 40+ lenders
Compare live mortgage interest rates from 40+ Dutch lenders and see what’s currently available in the market. Filter rates based on factors such as fixed-interest period, repayment type, NHG, loan-to-value (LTV) and energy label.
Do you want to know what your monthly mortgage payments could look like? Contact our mortgage advisors for a personalised mortgage report.
Please fill in all the fields to calculate the best interest rates for your persional situation
Dutch mortgage interest rates today – compare 40+ lenders
Compare live mortgage interest rates from 40+ Dutch lenders and see what’s currently available in the market. Filter rates based on factors such as fixed-interest period, repayment type, NHG, loan-to-value (LTV) and energy label.
Do you want to know what your monthly mortgage payments could look like? Contact our mortgage advisors for a personalised mortgage report.
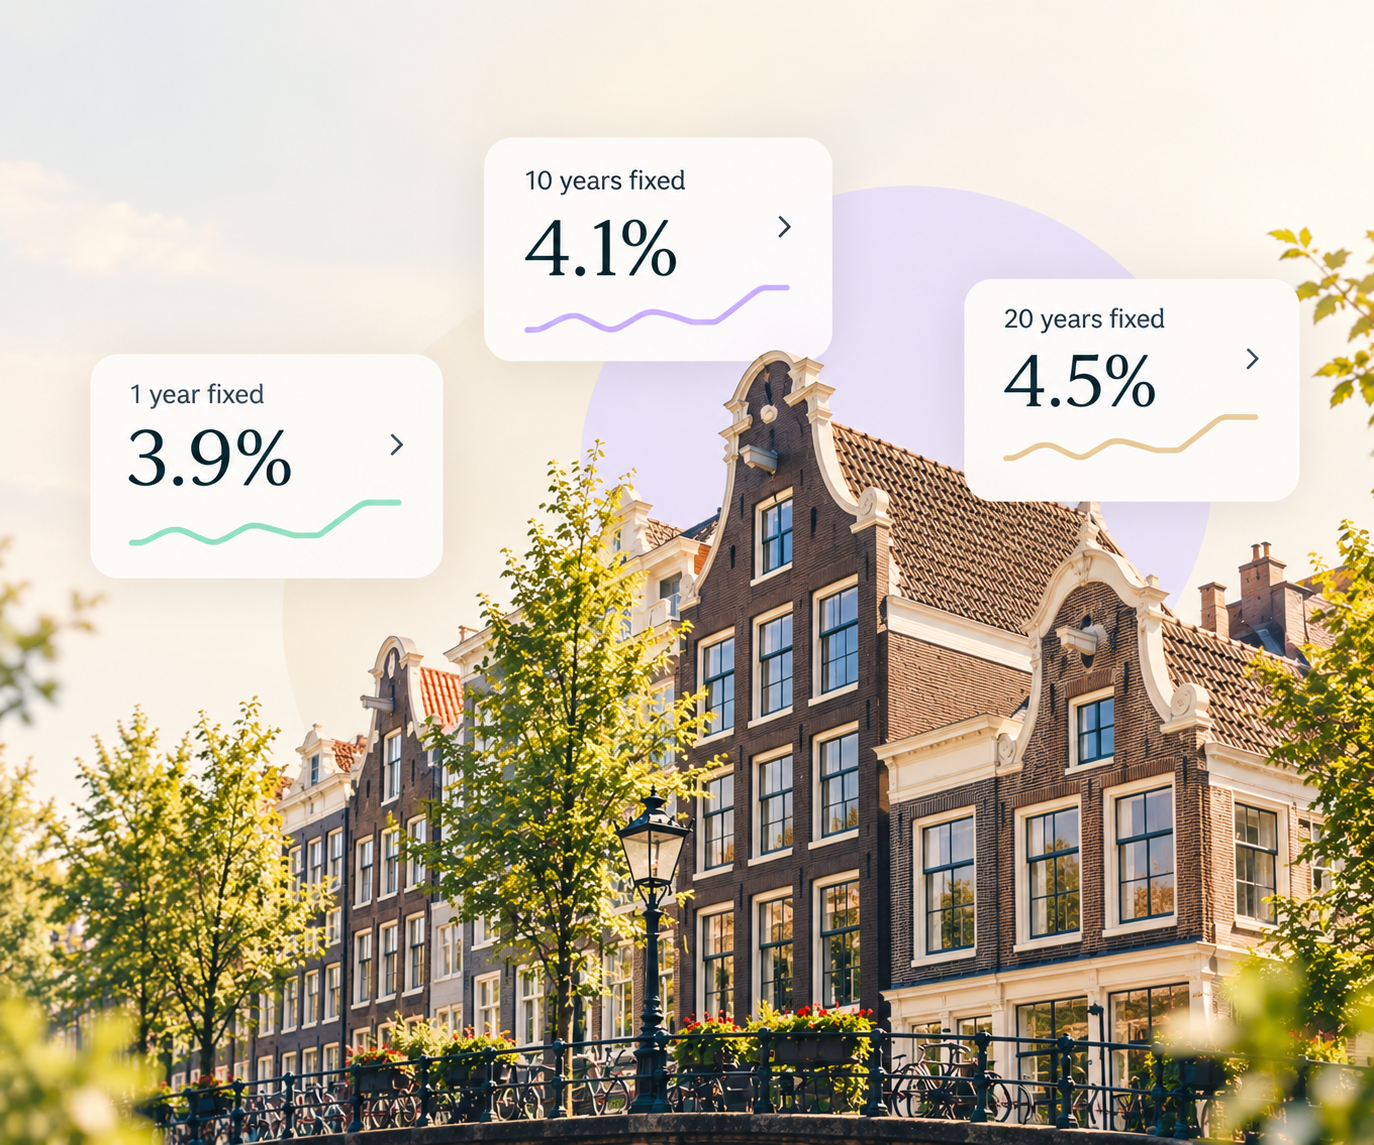
What should you look at when choosing a mortgage rate?
Our mortgage advisors help you compare lenders and understand which factors can increase or reduce the interest rate available to you. Some of the most important factors are:
Fixed-interest period – you can usually choose how long to fix your mortgage rate, for example 1, 5, 10, 20 or 30 years. Each fixed period has a different interest rate, so the right choice depends on your situation and how much certainty you want over your monthly payments.
Loan-to-value (LTV) and NHG – your rate can depend on how much you borrow compared with the value of your home. For example, lenders may offer different interest rates at 90% and 100% LTV. A mortgage with NHG (National Mortgage Guarantee) may also qualify for a discounted interest rate, as NHG reduces the financial risk for the lender.
Energy label – the energy efficiency of your home can also influence your mortgage. Some lenders offer interest-rate discounts for energy-efficient homes, such as properties with an A or B energy label. There may also be additional borrowing possibilities when you use the money to make your home more energy efficient.
Which is better: a fixed or a variable interest rate?
You don’t have to figure it out on your own. Our mortgage advisors explain how mortgage interest rates work, look at what is important to you, and help you understand the differences between fixed and variable rates. Together, we compare your options so you can make a well-informed choice that fits your situation and plans.
Fixed mortgage interest rate in the Netherlands
A fixed mortgage interest rate means your interest rate and monthly payments stay the same for a set period, usually between 5 and 10 years or longer.
This provides stability and peace of mind, as you know exactly what you will pay every month regardless of market changes.
Fixed rates are ideal for borrowers who prefer predictable payments and want to protect themselves from rising interest rates.
Variable mortgage interest rate in the Netherlands
A variable mortgage interest rate can change over time, based on market conditions and interest rates set by the Dutch Central Bank or European Central Bank.
In most cases, variable rates have lower rates than fixed rates, making them attractive for those who want to benefit from potentially falling rates.
However, monthly payments may increase if interest rates rise, so variable rates suit borrowers who are comfortable with some payment flexibility and risk.
FAQ
How does an annuity mortgage work?
With an annuity mortgage, you pay mostly tax-deductible interest (lower payments) at first and gradually repay more principal later—making it ideal for those expecting their income to rise over time.
Fixed monthly payments: you pay a consistent monthly amount that covers both the mortgage interest and principal repayment.
Mortgage payments: in the early years, most of your monthly payment goes toward interest, with a smaller portion repaying the loan. Over time, this gradually reverses.
Tax advantages: interest payments are tax-deductible, which reduces your net monthly costs. However, this tax benefit declines over time, meaning your net payments may rise even though your gross payment stays the same.
What is a linear mortgage?
With a linear mortgage, you repay an equal amount of the principal each month. As your outstanding mortgage balance decreases, you pay less interest, so your total monthly payments gradually decrease over time.
Fixed-principal repayment: You repay an equal portion of the principal every month, calculated by dividing the total mortgage amount by the number of months in the mortgage term.
Monthly mortgage payments: Since interest is calculated on the remaining principal, the amount of interest you pay decreases over time. As a result, your total monthly mortgage payments also decrease.
Tax benefits: You may be able to deduct the mortgage interest you pay from your taxable income if you meet the applicable conditions. Compared with an annuity mortgage, you repay the principal faster and generally pay less interest over the life of the mortgage.
How does an interest-only mortgage work?
With an interest-only mortgage, you pay interest each month without repaying the principal. This means the outstanding mortgage balance stays the same during the interest-only period.
Monthly payments: You pay interest each month without repaying the principal.
Mortgage interest deduction: For new interest-only mortgages, the interest is generally not tax-deductible. Different rules may apply to existing mortgages taken out before 2013.
Outstanding principal: The mortgage balance does not decrease, so you will still need to repay the outstanding amount at the end of the mortgage term.
Are expat mortgages in the Netherlands tax-deductible?
Mortgage interest can be tax-deductible in the Netherlands if you meet certain conditions. The same general mortgage interest deduction rules apply to expats who are subject to Dutch income tax rules. For mortgages taken out on or after 1 January 2013, some of the main requirements are:
Repayment: The mortgage generally needs to be fully repaid within 30 years on an annuity or linear repayment schedule to qualify for mortgage interest deduction.
Your main residence: The mortgage must be used to buy, improve or maintain a home that qualifies as your owner-occupied home.
Maximum period: Mortgage interest can generally be deducted for a maximum of 30 years. Different rules may apply to mortgages originally taken out before 1 January 2013.
Do expats get a higher interest rate?
No. In general, mortgage providers in the Netherlands offer the same interest rates to expats as they do to Dutch nationals.
Our happy clients
We are proud that so many clients appreciate the care, clarity, and high standards we bring to every mortgage journey.
Meet our mortgage advisors
Our mortgage advisors are here to help you get a clear insight into your mortgage options when you plan to move. We help you understand your situation and decide what makes the most financial sense.
Bart Kooijman
Mortgage Advisor

Robin Uijtdehaage
Mortgage Advisor
Luc Zwaan
Mortgage Advisor
Toni van der Flier
Mortgage Advisor